Tech Falters, Yields Slump on Oil, Meta's Spending
October 22, 2026
Oil spiked and stocks and yields sagged after a report that the U.S. and Israel might resume attacks on Iran next month. Meta's heavy spending outlook and chip worries also hurt.
Published as of: October 22, 2026, 9:16 a.m. ET
Listen to this article
Listen here or subscribe to the Schwab Market Update in your favorite podcast app.
| The markets | Last price | Change | % change |
|---|---|---|---|
| S&P 500® Index | 7,757.17 | +44.60 | +0.58% |
| Dow Jones Industrial Average® | 52,856.09 | +360.21 | +0.69% |
| Nasdaq Composite® | 26,702.86 | +278.04 | +1.05% |
| 10-year Treasury yield | 5.03% | -0.11 | -- |
| U.S. Dollar Index | 101.79 | -0.01 | -0.01% |
| Cboe Volatility Index® | 18.01 | +1.33 | +7.91% |
| Gold | $4,098.50 | -$51.50 | -1.23% |
| WTI Crude Oil | $99.30 | +$2.15 | +2.23% |
| Bitcoin | $81,690 | -$2,905 | -3.43% |
(Thursday market open) The market's old nemesis, rising crude oil prices, punctured the rally and sent stocks and yields into an early tailspin today despite Meta Platforms (META) and Tesla (TSLA) beating earnings expectations. Tech's positive momentum reversed, hurt by worries about heavy AI-related spending by Meta, Tesla, and others. Crude jumped on a New York Times report that the U.S. and Israel plan more attacks on Iran after the November 3 U.S. election.
Tech stays in the spotlight later with earnings from memory giant Western Digital (WDC) and Bloom Energy (BE), one of many energy firms helped by their association with AI power demand. Industrial giants Honeywell (HON), Lockheed Martin (LMT), and Union Pacific (UNP) all reported this morning. In data, initial weekly jobless claims fell to a historically low 194,000 and the September Leading Economic Index from the Conference Board looms at 10 a.m. ET with a 0.2% drop expected, Briefing.com said.
Wednesday featured a broad rally led by AI and other tech names after impressive earnings from SpaceX (SPCX) with solid growth in its AI business. Seven of 11 sectors rose, led by tech, though a weak outlook from Netflix (NFLX) hurt communication services. This morning, risk-off trading sent the 10-year Treasury note yield to a one-month low and weighed down bitcoin and metals.
To get the Schwab Market Update in your inbox every morning, subscribe on Schwab.com.
Three things to watch
- Tesla, Meta results gleaned: Meta topped quarterly estimates and expects capital expenditures of $135 billion to $145 billion in 2026. The bottom end of that is up slightly from before and possibly a reason for today's 2.7% drop in shares. It also pegged fourth quarter revenue between $73 billion and $76 billion, slightly above consensus. One disappointment was lack of a full-year 2027 revenue outlook, though Meta said it expects strong growth as AI investments benefit the core business. Another worry is continued heavy spending on AI and the third straight quarter of negative free cash flow. Tesla dove 4% early after earnings topped estimates and revenue met expectations but fell year-over-year as auto revenue declined. The quarter ended with Tesla's largest passenger vehicle backlog in four years. Tesla cited limited battery availability, one reason for possible pressure on shares. Enthusiasm over a possible merger between Tesla and SpaceX grabbed headlines. It could conceivably benefit both firms through cooperation on software, chip design, robotics, and connectivity, one analyst said. SpaceX fell 3% this morning, hurt by the tech selloff, after an 8% rise yesterday.
- Crude pulling strings: Today's early sell-off reminds investors that crude oil remains a direction setter on Wall Street even amid the parade of earnings. More attacks on oil vessels had investors worried yesterday even as The Wall Street Journal reported that exports of oil from the Middle East now exceed levels before the war. Exporters have found alternate routes to bypass the Strait of Hormuz. Product prices remain high, especially for diesel. Costly shipping remains a burden within the industry, and likely is getting passed along. Several companies, including United Airlines (UAL) and Philip Morris (PM), said in their earnings reports that rising energy costs are a burden. United cut the high end of its earnings guidance. U.S. weekly crude stockpiles, which traditionally rise toward the end of the year, fell more than three million barrels, the U.S. Energy Information Administration said Wednesday. Results from Union Pacific (UNP), Norfolk Southern (NSC), and Valero Energy (VLO) later today could give investors a better sense of crude's impact on transports and the energy industry.
- ECB, BoJ on tap next week along with Fed: Meetings of the Bank of Japan (BoJ) and European Central Bank (ECB) next week, along with next Wednesday's Federal Reserve rate decision, could help set direction for Treasury yields. Recent unrest in France, where the country's debt to gross domestic product ratio is above 100%, is in focus as the ECB gathers. "With elections not for another six months, France's bond market could remain a source of volatility," said Michelle Gibley, director of international equity research and strategy at the Schwab Center for Financial Research (SCFR). Debt concerns extend across the European Union amid heavy government borrowing, Reuters reported, with European banks particularly exposed, but banks are better prepared now than they were 15 years ago the last time Europe suffered a debt crisis. The ECB has raised rates twice this year compared with once for the Fed to fight inflation, and the International Monetary Fund said last week it expects another ECB hike this year. Higher rates overseas can sometimes hurt U.S. Treasuries, causing yields to climb.
Crypto currents
Treasury companies show anemic bitcoin buying: Digital asset treasury (DAT) companies, considered "buyers of last resort" at times during the latest crypto bear market, bought relatively little bitcoin even as the asset rallied nearly 40% starting in mid-August. The average 30-day net accumulation among DATs since bitcoin's bear market low on July 1 is 5,612 bitcoins. That's only about a fifth of DATs' average 30-day net accumulation during bitcoin's 30% rally from February 5 through May 5, and only about 15% of the average throughout the previous 12 months, according to Glassnode data. Most DATs have been under pressure for the past year. Many launched around the peak of the latest bull market, and were aggressive buyers when investors valued their shares at a premium to their underlying crypto holdings. But falling crypto and share prices have made it hard to issue new shares to buy crypto without diluting shareholders' existing shares.
" id="body_disclosure--media_disclosure--287546" >Treasury companies show anemic bitcoin buying: Digital asset treasury (DAT) companies, considered "buyers of last resort" at times during the latest crypto bear market, bought relatively little bitcoin even as the asset rallied nearly 40% starting in mid-August. The average 30-day net accumulation among DATs since bitcoin's bear market low on July 1 is 5,612 bitcoins. That's only about a fifth of DATs' average 30-day net accumulation during bitcoin's 30% rally from February 5 through May 5, and only about 15% of the average throughout the previous 12 months, according to Glassnode data. Most DATs have been under pressure for the past year. Many launched around the peak of the latest bull market, and were aggressive buyers when investors valued their shares at a premium to their underlying crypto holdings. But falling crypto and share prices have made it hard to issue new shares to buy crypto without diluting shareholders' existing shares.
On the move
- AI and chip stocks led early selling today, a reversal of what's been strength this week in the sector. Some of the names falling most included Lumentum (LITE), Arm Holdings (ARM), Marvell Technology (MRVL), Applied Materials (AMAT), and Intel (INTC). All fell 4% or more ahead of the open.
- CoreWeave (CRWV), a recent focus of investors worried about AI-related debt loads, fell 3.6%, and Dell (DELL), which has benefitted from AI-related demand for its products, fell 4.6%.
- Lam Research (LRCX), a maker of equipment used to build chips, fell 7% after its earnings late Wednesday. Results beat expectations but guidance only met expectations—a disappointment to investors hoping for signs of even more optimism over chip and AI spending.
- Texas Instruments (TXN) fell almost 1% after earnings and guidance for the chip firm topped estimates. The company's sales forecast also exceeded consensus, helped by automotive and industrial demand.
- IBM (IBM) dropped nearly 6% despite earnings and revenue topping analysts' estimates. The company also raised its outlook. The company's 4.7% quarterly revenue growth year over year was down from 9.5% annual growth in the first quarter, Barron's noted, possibly a reason for selling.
- Spotify (SPOT) jumped 7% early after quarterly results showed subscribership growing faster than Wall Street had expected and gross margin exceeding earlier guidance. Fourth quarter guidance also impressed.
- Lockheed Martin soared to 4% early gains, lifted by earnings per share and revenue beating analysts' expectations and a rise in guidance for fiscal 2026 earnings per share.
- Crypto-related stocks like Strategy (MSTR), Circle Internet Group (CRCL), and Coinbase (COIN) retreated early today in risk-off trading after strong gains Wednesday.
- Applied Digital (APLD) soared 8% Wednesday on news of a data center agreement with Solaris Energy Infrastructure (SEI), shares of which rose almost 10%.
- Utility and energy firms expected to benefit from AI rose sharply Wednesday, including Constellation Energy (CEG), Bloom Energy (BE), and GE Vernova (GEV).
- United Airlines (UAL) rose 4% Wednesday despite narrowing earnings guidance, lifted by optimism about demand, CNBC reported.
More insights from Schwab
Magnificent Seven march to different drummers: Our new feature compares and contrasts the Magnificent Seven stocks, pointing out how price dispersion among them reflects their lack of uniformity in the products they sell and the markets they address.
Political headlines and the market: The latest episode of Schwab's WashingtonWise podcast helps investors understand how the noise around coming U.S. elections might affect the market and checks possible scenarios if one or both chambers of Congress change party control. The focus is on portfolio implications for the federal debt, interest rates, AI regulation, and more.
Higher yields and retirement income: Rising yields may offer retirees more income potential, but that doesn't mean one should build a portfolio around yield alone. Schwab's latest look at fixed income explains how people in retirement can approach the current yield environment.
Chart of the day
Data source: CME Group. Chart source: thinkorswim® platform.
Past performance is no guarantee of future results.
For illustrative purposes only.
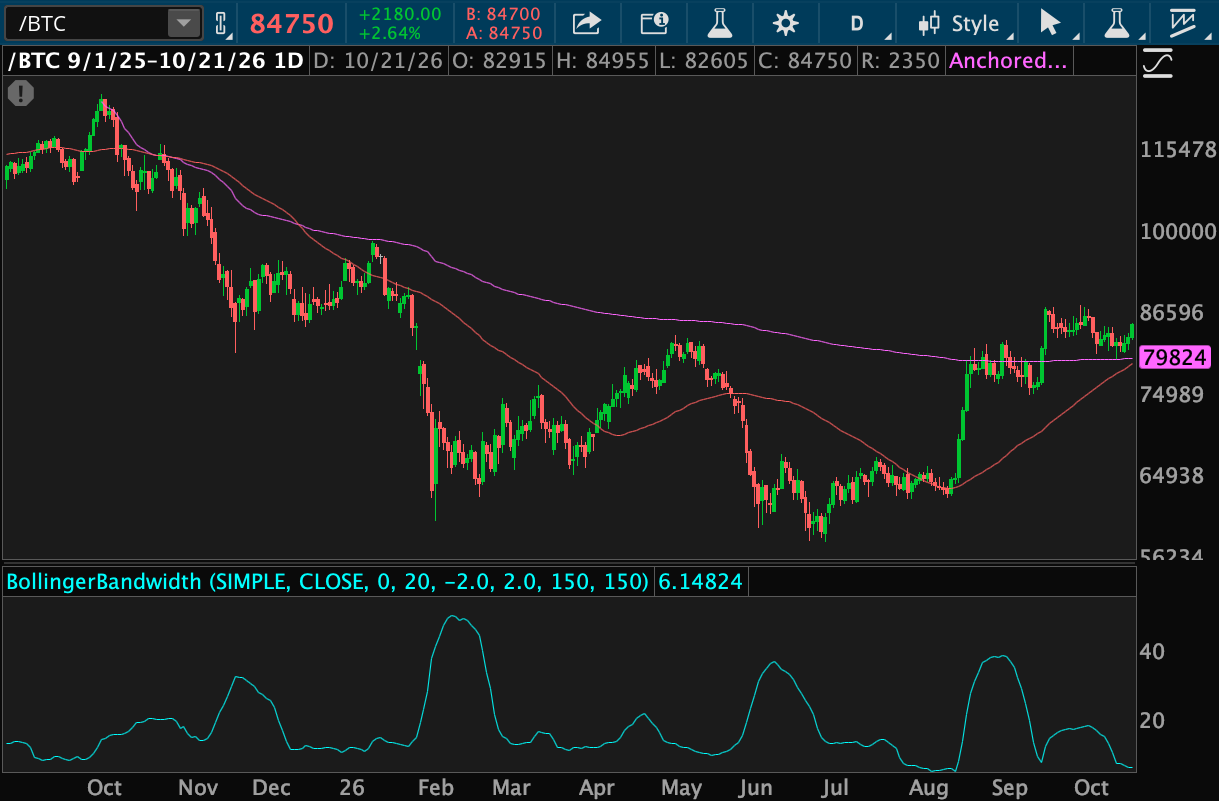
Bitcoin futures (/BTC—candlesticks) have traded mostly sideways in recent weeks after hitting the highest level since January, testing support at the Anchored Volume-Weighted Average Price (purple line) and the 50-day simple moving average (red line). A gauge of Bollinger Band width (lower pane) shows extremely compressed volatility, which can often precede a big move up or down.
The week ahead
October 23: October S&P Global U.S. manufacturing and services PMIs, October final University of Michigan Consumer Sentiment, and expected earnings from American Express (AXP), Illinois Tool Works (ITW), SLB (SLB).
October 26: Expected earnings from Verizon (VZ), Welltower (WELL), Cadence Design Systems (CDNS), Nucor (NUE), and Public Storage (PSA).
October 27: September durable goods, October Consumer Confidence, September new home sales, and expected earnings from Coca-Cola (KO), Novartis (NVS), Boeing (BA), Corning (GLW), Freeport-McMoRan (FCX), HCA Healthcare (HCA), Johnson Controls (JCI), American Tower (AMT), United Parcel Service (UPS), Visa (V), Seagate (STX), Waste Management (WM), NXP Semiconductors (NXPI), Baker Hughes (BKR), and Teradyne (TER).
October 28: FOMC rate decision and expected earnings from Microsoft (MSFT), Alphabet (GOOGL), T-Mobile (TMUS), ServiceNow (NOW), GE Vernova (GEV), Amphenol (APH), UBS (UBS), Phillips 66 (PSX), and Vertiv (VRT).
October 29: Third quarter GDP, September PCE prices, September core PCE prices, and expected earnings from Amazon (AMZN), Eli Lilly (LLY), Intel (INTC), Sandisk (SNDK), Gilead Sciences (GILD), Mastercard (MA), Merck (MRK), Caterpillar (CAT), Shell (SHEL), Anheuser-Busch Inbev (BUD), Bristol-Myers Squibb (BMY), Altria (MO), Stryker (SYK), Starbucks (SBUX), and Mondelez (MDLZ).